The Fortified Saver: A Practical Guide to Deposit Protection in 2026
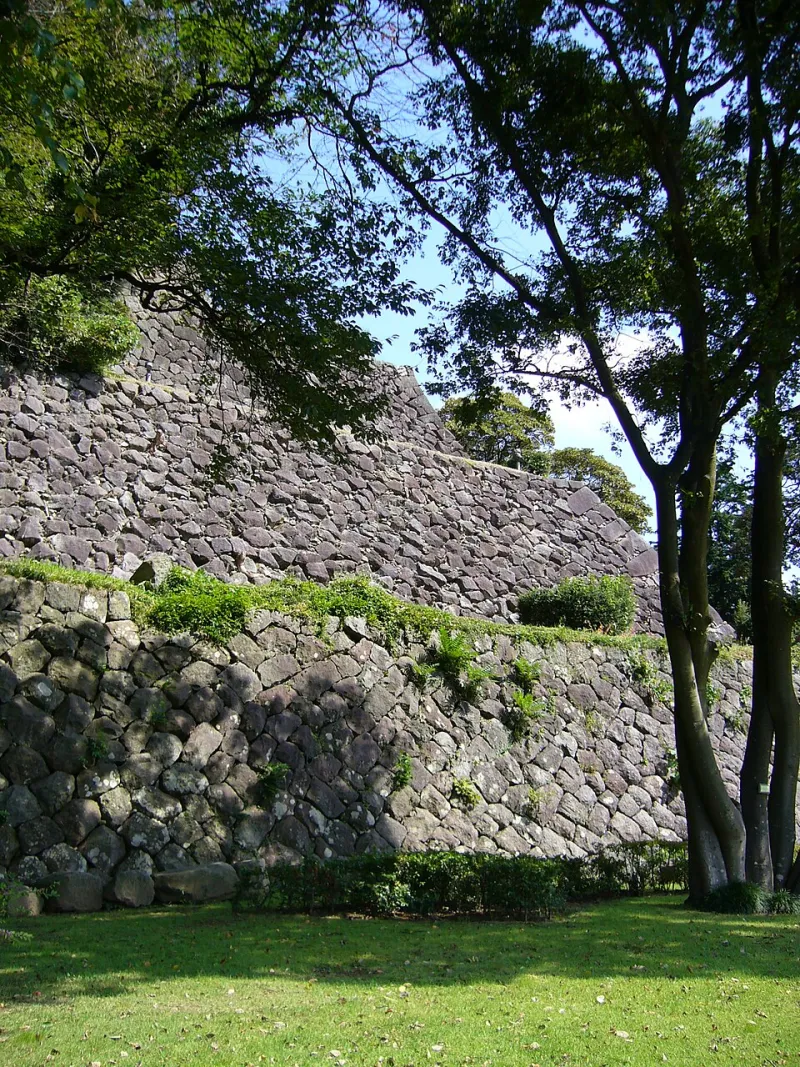
Photo: Asanagi, CC0, via Wikimedia Commons
Deposit protection is one of those subjects that sounds more forbidding than it is. For most savers, the Financial Services Compensation Scheme - usually known as the FSCS - performs a simple function: if a bank or building society fails, it returns eligible deposits up to a set limit. In 2026 the standard limit is £85,000 per eligible person, per authorised firm. Think of that figure as the height of a castle wall. Money inside the wall is protected; money above it is exposed.
That image is useful because it explains both the strength and the limit of the scheme. The wall is not there to stop you saving more. It is there to mark the point at which protection ends and ordinary risk begins.
A wall around each firm, not each account
The most common misunderstanding is that the £85,000 limit applies to each account. It does not. It applies to each eligible person, per authorised firm. If you hold £50,000 in a savings account and £50,000 in a fixed-term bond with the same bank, the two balances are added together. On a straightforward reading, £85,000 would be protected and £15,000 would sit above the wall.
The same logic applies to brands. Several banks and building societies operate more than one trading name under a single banking licence. Two accounts with different logos may therefore share one protective wall. Before assuming that your savings are spread, check the firm's authorisation and the FSCS register. The practical question is not 'how many accounts do I have?' but 'how many authorised firms am I relying on?'
Which deposits sit inside the wall
FSCS protection is designed for eligible deposits held with UK-authorised banks, building societies and credit unions. That includes many familiar current accounts, savings accounts and cash ISAs. It does not follow that every financial product sold by a bank is covered in the same way. Investments, pensions and some insurance products sit under different rules, and some products may not be eligible at all.
The sensible check is to look for clear FSCS information in the product terms and to confirm the firm's status on the FSCS website or the Financial Conduct Authority register. If a rate looks unusually generous, the question to ask is not only 'what does it pay?' but 'what is protecting it?' A high rate is not a substitute for a protected deposit, and protection is not a reason to ignore the quality of the product.
Temporary high balances: a wider gate for life's big moments
There is an important exception for large sums that arrive through certain life events. In defined circumstances, protection can rise to £1 million for a temporary high balance, typically for six months. Examples can include proceeds from selling your main home, an inheritance, an insurance payout or a divorce settlement.
This is not a general uplift for wealthy savers. It is a time-limited allowance for money that is passing through your hands after a significant event. The details matter, including the length of the protection period and the evidence required if a claim is ever needed. Anyone expecting a large sum should check the current FSCS guidance before deciding where to place the money.
Joint accounts and the arithmetic of shared walls
A joint account is treated differently because there are two eligible depositors. In broad terms, each holder has their own £85,000 limit with the same firm, so a joint account can be protected up to £170,000. That does not create a separate wall for every account. Each person's share is still counted alongside any sole accounts they hold with the same firm.
Suppose two people hold £170,000 in a joint account and one of them also has £20,000 in a sole savings account with the same bank. The joint balance is generally treated as shared equally, so each person has £85,000 from the joint account. The person with the sole account then has a total of £105,000 with that firm. On a simple reading, £20,000 of that person's money would sit above the protected limit.
The arithmetic is not a reason to avoid joint accounts. It is a reason to keep a clear map of where the money is held.
Practical checks for keeping savings inside the net
First, confirm the firm is authorised and check how it is grouped for FSCS purposes. Second, add up all eligible deposits you hold with the same firm, including accounts under different brand names. Third, spread larger balances across separate authorised firms if protection matters to you. Fourth, use joint accounts deliberately, not accidentally. Fifth, review the position after a merger, a rate change or a large deposit arrives.
It also helps to keep simple records: account numbers, firm names, maturity dates and the basis on which each account is held. If a firm fails, protection is designed to work without unnecessary drama, but clear records make any claim easier to understand.
Protection is a floor, not a full financial plan
The £85,000 limit is a robust feature of the UK savings system, but it is not a complete financial strategy. It does not remove the need to compare rates, keep an emergency fund or think about access to your money. It simply sets a boundary around one specific risk.
A well-built savings plan uses the wall for what it is: a strong defence against the failure of an authorised firm. Within that wall, savers can still make ordinary, sensible choices about rate, term and access. The castle is not complicated. It is simply worth knowing where its walls stand.